A lesson for financial advisors about identity, coaching, rest, and the courage to question what we think we know
By Dr. Vicki Rackner
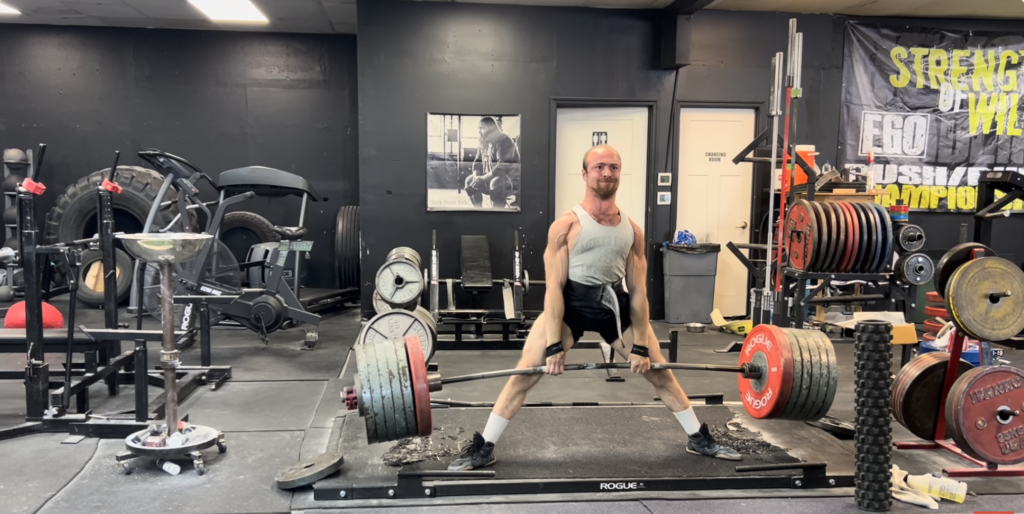
My 145-pound son recently deadlifted more than 600 pounds. That is more than four times his body weight – and a new personal record.
The video lasts only a few seconds. The achievement took years.
As I watched him complete the lift, I felt the pride any mother would feel. But I also saw something else: a vivid picture of what it takes to pursue an ambitious goal. His experience has lessons for financial advisors and the clients they serve.
It helps to love the hard thing
Powerlifting is hard. My son regularly bumps up against the limits of what his body can do. Progress is not linear. Some training sessions feel strong; others are disappointing. Injuries and setbacks can interrupt the plan.
Yet he keeps returning because he loves it. Powerlifting is not merely an activity on his calendar. It has become part of his identity. He says, “I am a powerlifter.”
That distinction matters in financial planning. Many clients approach a financial goal as something they should do: save more, spend less, review their insurance, complete their estate plan, or finally look at the numbers they have avoided. A duty can produce short bursts of compliance. Identity is more durable.
A client who says, “I should save more” is in a different psychological place from a client who says, “I am someone who takes care of my future self.” A physician who says, “I need to get around to disability insurance” is in a different place from one who says, “Protecting my ability to earn is part of how I care for my family.”
The advisor cannot manufacture passion. But the advisor can help connect an abstract financial task with something the client already loves: family, freedom, generosity, meaningful work, or the ability to make choices without fear.
Big goals need visible milestones
My son did not begin by announcing that he would lift more than 600 pounds. His first big goal was a 500-pound deadlift. He trained until he achieved it. Then he set his sights on 600.
It took years. The number gave his effort a destination, but the smaller training targets gave him a path.
Financial advisors understand the mathematics of goal setting. Yet a technically precise projection is not always a psychologically useful goal. “Accumulate $4.2 million by age 65” may be mathematically sound, but it can feel remote and emotionally flat.
A client may engage more readily with milestones that can be seen and felt: building a three-month emergency reserve, paying off one loan, increasing a retirement contribution by one percentage point, protecting income, or funding one year of a child’s education.
The long-term goal still matters. But people need evidence that their effort is working. Each milestone provides that evidence and builds confidence for the next lift.
The plan works only when the client can follow it
My son has coaches who design a training regimen to help him reach his goals. They determine when he should lift, how much he should lift, and when he should back off.
Sometimes he “cheats” on the plan – but not in the way you might expect. He does not skip training. He does too much.
He overtrains.
More effort feels as if it should produce faster progress. In reality, training creates stress; recovery allows the body to adapt. When he ignores the recovery period, he can paradoxically slow his progress.
Financial clients can do their own version of overtraining. Motivated by fear or enthusiasm, they may commit to a savings target they cannot sustain, cut every source of enjoyment from the budget, or try to repair years of inattention in a single month. The plan may look impressive on paper and still fail in real life.
A good advisor does more than prescribe the maximum mathematically possible action. A good advisor helps the client find a sustainable pace. Sometimes the most productive recommendation is to do less, consolidate the next steps, and allow a new habit to take hold.
Rest is not a failure to train. Recovery is part of the training plan. In the same way, room for life is not a failure of financial discipline. A plan that a client can live with is more valuable than a perfect plan the client abandons.
Do not confuse conventional wisdom with universal truth
The most important lesson my son taught me had little to do with goals or discipline. It was a lesson in humility.
He began powerlifting after seeing videos suggesting that lifting could help alleviate back pain. He did not tell his surgeon mother. He knew I would try to prohibit it.
After all, everybody “knows” that heavy lifting will make back pain worse.
Except that, for him and some other lifters, it helped.
To be clear, I am not recommending powerlifting as a treatment for back pain. Anyone experiencing back pain should seek individualized guidance from a qualified health professional. My point is different: I would never have explored the possibility because I believed I already knew the answer.
Financial advisors face this danger, too. Expertise is valuable. It can also create blind spots. When a physician client delays a decision, spends in a way that appears irrational, or resists a recommendation that seems obviously beneficial, it is tempting to decide that the client is stubborn, irresponsible, or unmotivated.
What if that interpretation is wrong?
The behavior may make sense when you understand the physician’s world: years of delayed gratification, medical-school debt, a late start to earning, responsibility for other people’s lives, fear of making another consequential mistake, exhaustion, or a deep need to preserve autonomy.
Curiosity changes the conversation. Instead of asking, “Why won’t this client follow my advice?” you might ask, “What makes this recommendation difficult to act on?” Instead of repeating the logic more loudly, you can investigate the story beneath the choice.
The advisor as coach
A powerlifting coach does not walk onto the platform and complete the lift for the athlete. The coach contributes expertise, observes what the athlete cannot see, adjusts the plan, and helps the athlete prepare for the moment when the weight is in the athlete’s hands.
That is also a useful description of financial advice.
Your client must ultimately make the decision, tolerate the uncertainty, and perform the next action. Your value is not limited to knowing the answer. It includes helping the client connect the answer to a meaningful identity, break the goal into achievable milestones, maintain a sustainable pace, and recognize when an old assumption is getting in the way.
Questions worth asking
My son’s 600-pound deadlift left me with questions that apply far beyond the gym. They may also be useful in your next client conversation:
What does this client care about enough to keep going when the work becomes difficult?
How could the desired behavior become part of the client’s identity?
What visible milestone would help the client experience progress?
Is the plan sustainable, or is the client trying to change too much at once?
What assumption am I making about this client’s behavior?
What might I learn if I asked, “What if I’m wrong?”
My son’s achievement opened my eyes to what is possible. Who would imagine that a person could lift more than four times his body weight?
Clients may be capable of more than they imagine, too. The advisor’s job is not to push harder at every turn. It is to help clients discover what matters, prepare wisely, recover when needed, question the assumptions that constrain them, and perform the next lift.